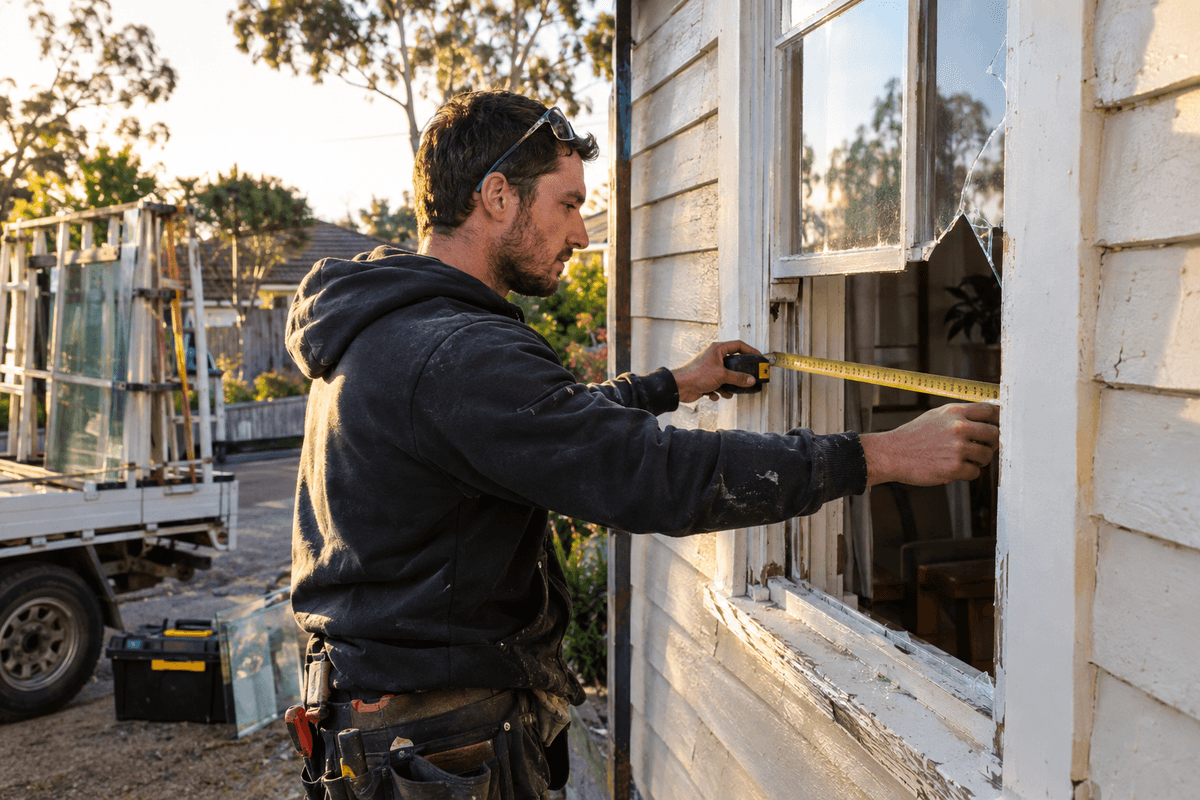

Every quote contains a margin, and every completed job contains a different one. For service, trade and project businesses the second number is usually smaller, eroded by hours that didn't get counted, materials that never hit an invoice, variations absorbed as goodwill and stock that simply wandered. Each leak is too small to notice on its own; across a year they compound into the gap between the profit you planned and the profit you got. Job costing — comparing actuals to quote on every job, and feeding the result into the next quote — is the discipline that closes it.
Where the margin goes
Uncaptured labour
The dominant leak in service businesses. The quoted hours become more hours in reality: the return trip for the forgotten part, the "while you're here" favour, the apprentice's rework. But the timesheet often says what the quote said, because hours get reconstructed on Friday from memory, and memory is generous. The fix is capture at the time, against the job — a field app, a job card, even a disciplined paper docket, anything except reconstruction. If a job number isn't attached to the hour when the hour happens, that hour tends to vanish into overhead.
Unbilled materials
Materials grabbed from the van or storeroom without being allocated to a job, consumables nobody itemises, the special-order part that arrived after the invoice went out. The principle is simple: everything that crosses onto a job gets recorded against it, whether by barcode scanning where volume justifies it or a strict dockets habit where it doesn't.
Variations absorbed as goodwill
The customer's "while you're at it" that adds real hours and materials and no revenue. The cure is cultural as much as procedural. Give the whole team one standard sentence they're trained to say cheerfully: happy to do that, it sits outside the quote, so we'll confirm the addition before starting. Then make the variation process nearly frictionless (a two-line message and a photo is plenty), because a variation process that takes longer than the variation will always be skipped.
Wandering stock
Inventory shrinkage in a service business rarely looks like theft; it looks like untidiness. Vans carrying uncounted stock, returns that never make it back to the shelf, warranty swaps recorded nowhere. Count the stock periodically against what the system says you hold, and treat the variance as a finding rather than a shrug. A discrepancy is unbilled work, shrinkage or chaos, and all three deserve names. Investigated honestly, the count usually reveals process holes rather than villains, and closing a process hole fixes every future job at once.
Cost labour at the loaded rate
The payslip figure is not what an hour of labour costs you. The true rate carries the wage plus super, leave provisions, workers compensation, training time, the vehicle, the tools and a share of supervision. Work out your loaded rate once for each role and quote from that number, because a business quoting from payslip rates can be busy all year and still go backwards; the busier it gets, the faster the loss compounds. Confirm the wage inputs themselves against your award or agreement rather than folklore.
Close the loop on every job
Job costing only earns its keep when the comparison actually happens. When a job closes, put quoted hours next to actual hours and quoted materials next to actual materials, and give the variance one honest sentence: underquoted, poorly scoped, badly run or unlucky. Then review the pattern monthly rather than agonising job by job. Certain job types, customers or crews will keep appearing on the wrong side, and that pattern is the most valuable pricing intelligence your business produces, because it comes from your own operations rather than anyone else's benchmark.
Feed it forward
The endpoint is a loop: quote from history, capture actuals as they happen, review the variance, and let the variance sharpen the next quote. None of it requires elaborate software; most accounting platforms and field-service tools carry adequate job costing if you switch it on and use it consistently. What it does require is the habit, held long enough to trust the data, which is really a question of systemising the capture so the information arrives without heroics. Margin leaks are rarely dramatic. They're just unmeasured, and measurement is most of the repair.
About the author
Nick Lucock
Chief Executive Officer, Valont
Nick leads Valont's day-to-day operations across Finance, People, Operations and Growth. He writes about how the work actually gets done, the processes, systems, and tools that keep Australian SMEs compliant and growing.
LinkedIn →