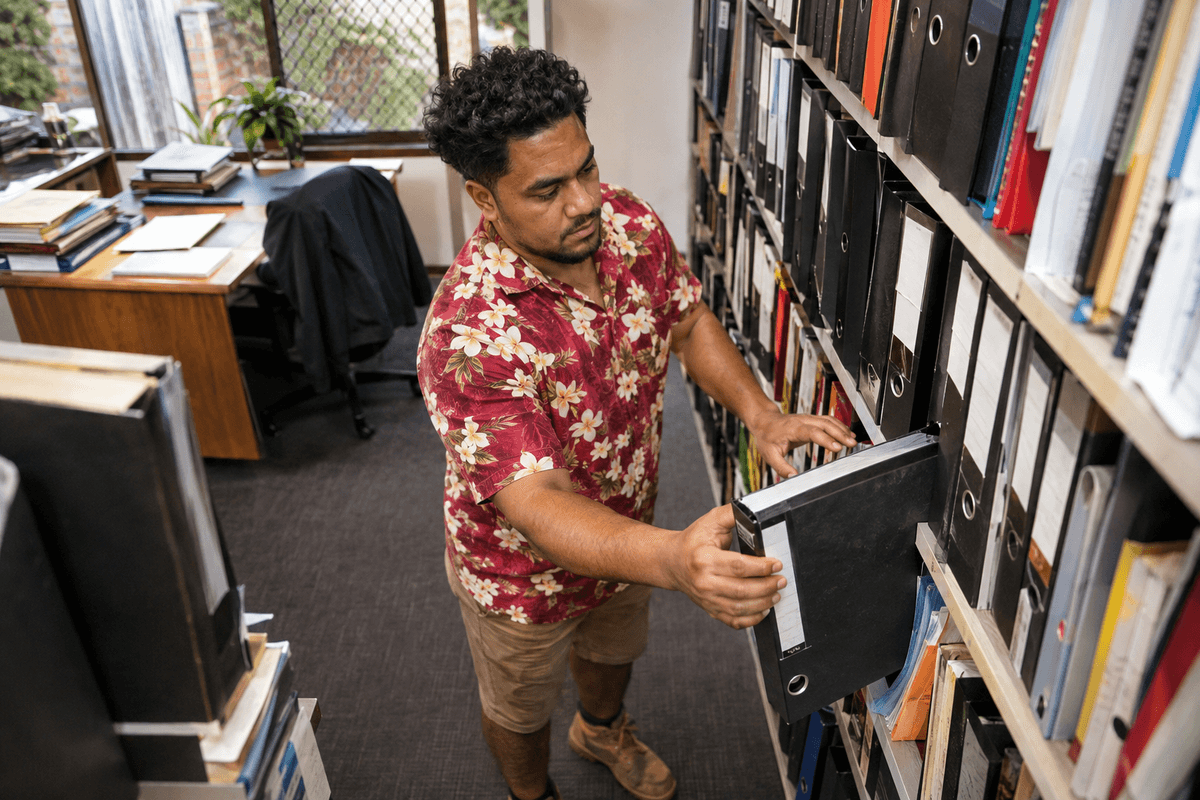

The stocktake occupies a special place in business folklore: the pizza-fuelled all-nighter, the clipboard chaos, the final number that everyone quietly distrusts. None of that is intrinsic to counting things. A clean stocktake is won in the two or three weeks before the count — in tidying, clearing, cut-off discipline and method decisions — and the count itself becomes a few organised hours producing a number you can actually use. With calendar-year-end counts approaching for many businesses (and the same playbook applying to June counts), here's the preparation sequence.
Why the count matters more than it feels like it does
Before the how, the why — because stocktake effort tracks belief. The stock figure directly sets your cost of goods sold, which sets your gross margin, which sets your profit: an inventory error flows dollar-for-dollar into the P&L, in whichever direction. It's also the moment shrinkage, damage and dead stock get measured (the variance between what the system says and what the shelves hold is a diagnostic, not an embarrassment), the input your accountant needs for tax, and — for any business carrying serious inventory — a working-capital snapshot: every counted dollar on the shelf is a dollar not in the bank. A casual count doesn't just risk a wrong number; it wastes the one scheduled moment the business looks honestly at its second-biggest asset.
The fortnight before: shrink the job
Sell and clear deliberately. The cheapest item to count is the one you sold first. A pre-count clearance push — the aged stock, the discontinued lines, the seasonal leftovers — converts counting work into cash and shrinks the job. What can't be sold gets dispositioned now: damaged goods written off and removed, returns processed, consignment and customer-owned items segregated and labelled (counting other people's stock as yours is a classic variance generator).
Tidy into countable locations. Most counting time is searching time. The pre-week sweep: like items consolidated, locations labelled, the mezzanine archaeology sorted, vans and site stock returned or scheduled for remote counting, and the "miscellaneous" shelf — every warehouse has one — dispersed to proper homes. A tidy warehouse counts in half the time and, not coincidentally, runs better all year.
Clean the data side. The count compares shelves to system, so the system needs to be matchable: units of measure consistent (the eternal each-versus-box confusion produces more variance than theft), open purchase orders receipted or cancelled, invoiced-but-not-shipped and shipped-but-not-invoiced items identified. This is also when you decide the cut-off: a count date and time after which movements pause or are logged separately. Cut-off failures — goods received during the count, sales processed mid-count — are the leading cause of numbers nobody can reconcile afterwards.
Decide the method before the day
Three decisions, made in advance and written down. Who counts what: teams of two (one counts, one records), zones assigned, counters not counting their own everyday area where practical — fresh eyes find what familiarity skips. How it's recorded: scanner/app-based if your system supports it (faster, fewer transcription errors), pre-printed count sheets without system quantities shown if not (blind counts beat confirmation-bias counts). And the variance protocol: significant discrepancies get an immediate recount by a different person, and the threshold for "significant" is set beforehand so the day doesn't descend into ad-hoc judgement. Add the supporting cast — labels, scanners charged, a controller who owns the master sheet and the cut-off — and the day runs like the process it now is.
After: the part most businesses skip
The count's value is realised in the 48 hours after. Investigate the material variances while memories are fresh (miscounts, unit confusion, receipting gaps, and yes, sometimes shrinkage worth a harder look); post the adjustments promptly so the accounts reflect reality; and write the half-page of lessons — the locations that were chaos, the items that defeated the unit system, the cut-off wobbles — into next count's prep list. Businesses that run this loop find their counts get faster and their variances smaller every cycle, which is the quiet sign that inventory control is improving year-round. We'll cover reading the results — what the variance and ageing patterns should change about buying and pricing — in a companion piece when the counting season lands.
FAQ
Do we legally have to do a year-end stocktake?
Businesses carrying inventory generally need a defensible stock figure for tax and accounts; physical counts are the standard evidence. Smaller operations within turnover thresholds may have simplified options where stock levels haven't moved materially — confirm your position with your accountant rather than assuming.
Could we use rolling/cyclic counts instead of one big one?
Yes — counting sections continuously through the year (with good system discipline) can replace or shrink the annual event and catches problems months earlier. It suits businesses with solid inventory systems; the annual full count remains the reset button and the auditor's friend.
What about work-in-progress?
WIP needs its own valuation pass — materials plus labour at cost on unfinished jobs — and it's the most commonly fudged figure in service-adjacent businesses. Agree the method with your accountant once and apply it consistently; a defensible estimate beats a heroic guess.
Inventory discipline shows up directly in margin and cash. Our free Business Health Check takes five minutes and tells you which levers need attention.
If this is the problem you are working on, Valont’s Operations hub runs it support and cybersecurity as part of a connected back office, and the cyber health check shows where to start.
About the author
Nick Lucock
Chief Executive Officer, Valont
Nick Lucock is the Chief Executive Officer of Valont and leads its day-to-day operations across Finance, People, Operations and Growth. He runs the team that does the work Valont publishes about: the bookkeeping, BAS and payroll runs, the award interpretation on every pay cycle, the IT and security layer, and the advisor cadence that keeps an owner's back office current. Nick writes the practical side of Valont's library, the processes, systems and tools that keep Australian SMEs compliant and growing, and he is the author of most of the operational articles on the site. He works with owners across construction and trades, health, hospitality and professional services.
LinkedIn →